
Uganda and the World Bank have agreed to accelerate implementation of a $4.6 billion development portfolio covering 18 operations, as the government moves to address project delays and improve the use of development financing.
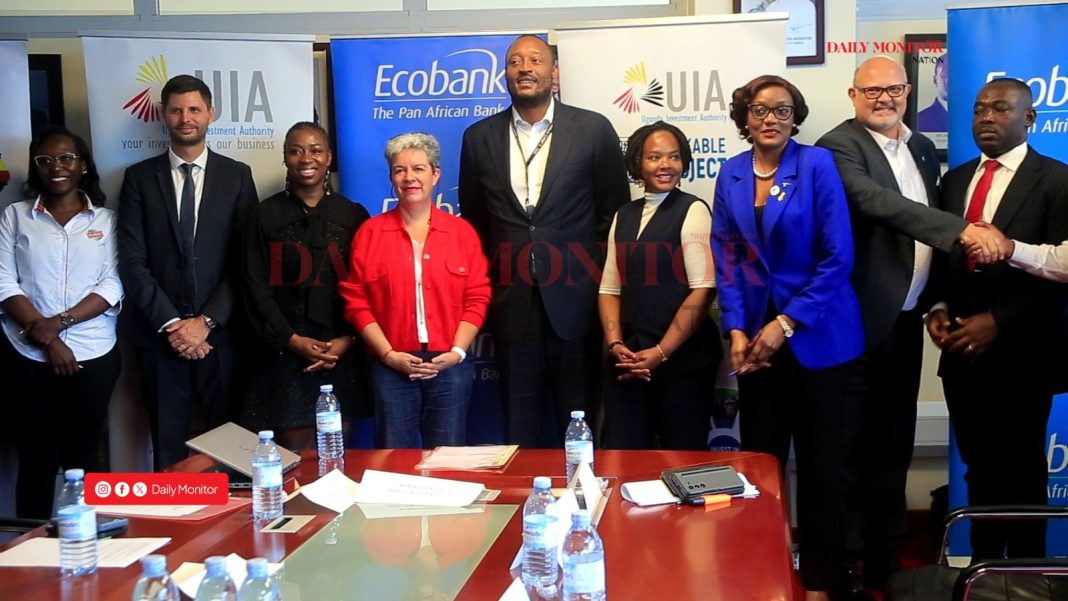
The commitment was made during a Uganda-World Bank Country Portfolio Performance Review in Kampala, which examined implementation progress and identified bottlenecks affecting project delivery.
Government seeks to separate funding and management delays
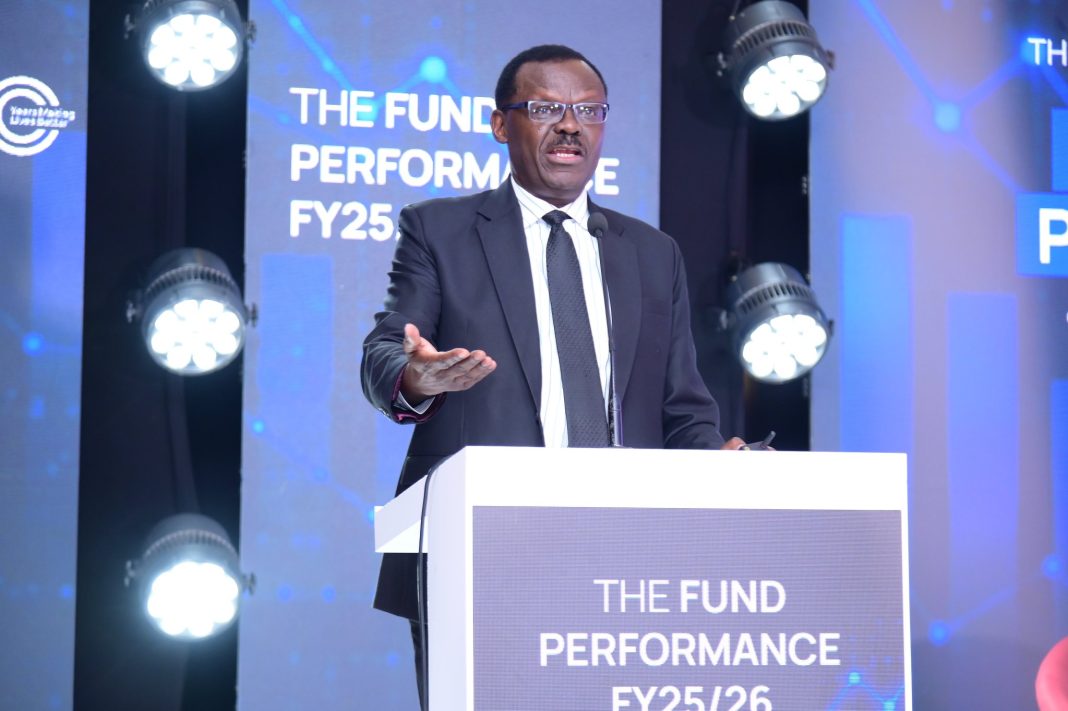
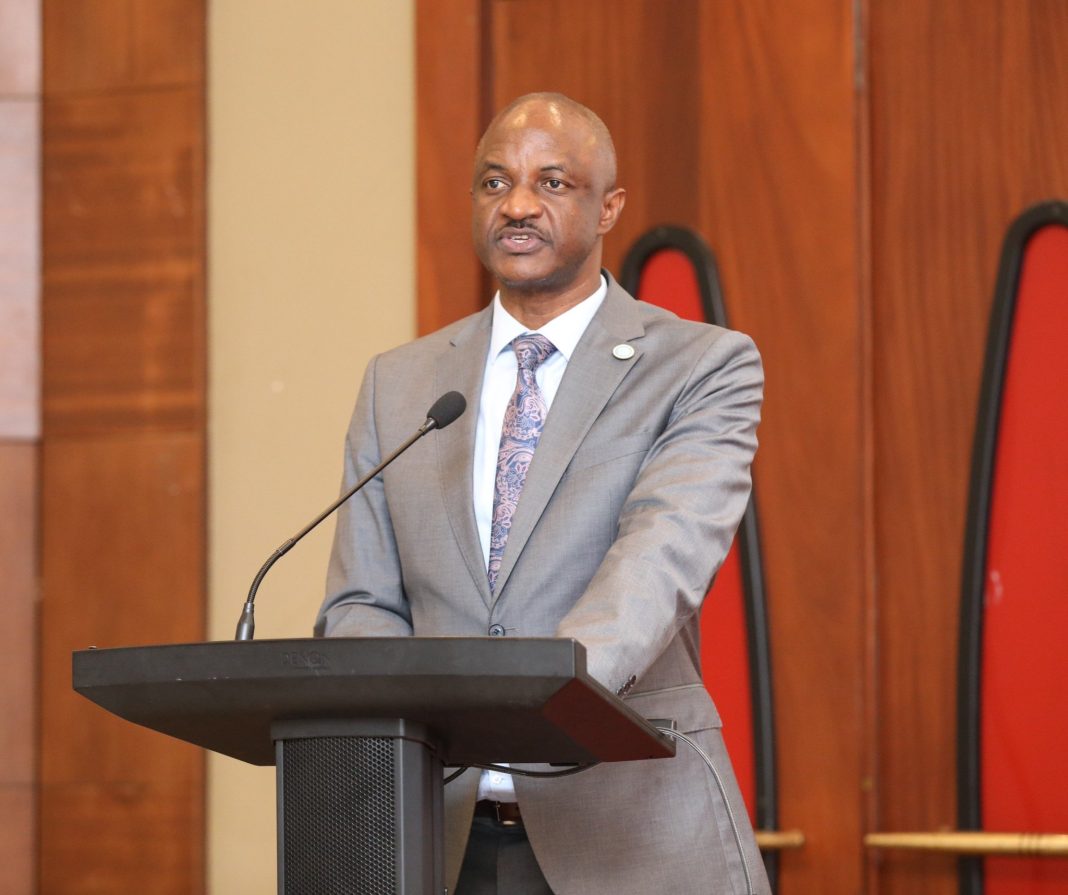
Uganda’s Permanent Secretary and Secretary to the Treasury Ramathan Ggoobi said the government was assessing whether delayed projects were being held back by funding constraints or management problems.
“We are going to get quantified answers that separate the fiscal constraint from the management constraint,” Ggoobi said.
He cited procurement, project designs, land acquisition, counterpart funding, approvals and contract management among the factors affecting implementation.
Ggoobi said some projects were being committed before they were ready, resulting in physical works starting as late as the third year of implementation.
That reduced the time available to complete projects and increased the risk of extensions, incomplete works and higher costs, he said.
Uganda tightens project readiness requirements
Ggoobi said the government had strengthened project gatekeeping under the Public Investment Management System to ensure projects meet required conditions before negotiations and financing agreements.
The requirements include approved procurement plans, completed environmental and social safeguards and acquisition of necessary rights-of-way.
He also identified electronic government procurement as a key reform to improve efficiency, transparency and accountability.
All Programme-for-Results operations are required to use the system, while Uganda will continue discussions with the World Bank to extend its use to other projects, he said.
Nine projects face 2027-28 closure deadlines
Nine projects in the portfolio are scheduled to close in 2027 and 2028, increasing pressure on implementing agencies to accelerate delivery.
Ggoobi said projects unlikely to be completed within their remaining implementation periods should be considered for restructuring, scaling down or cancellation.
Extensions should be limited to essential ongoing contractual obligations, he said.
The government wants each project to have a clear improvement plan setting out the required action, responsible institution, financing implications and implementation timeline.
Persistently underperforming projects could face restructuring or termination.
World Bank says $3.1 billion remains undisbursed
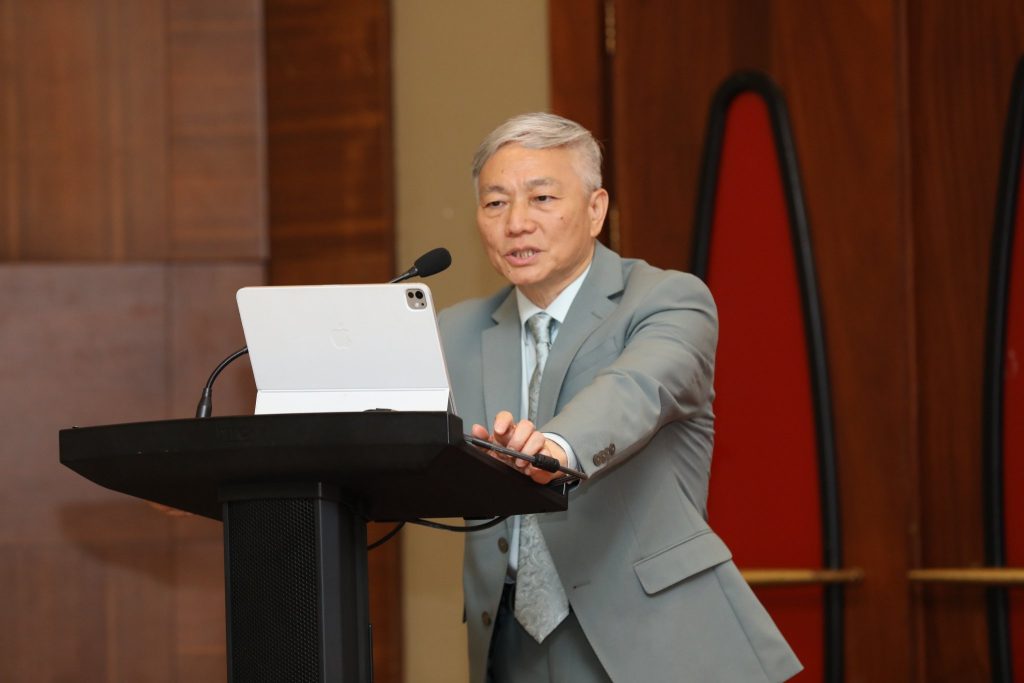
Qimiao Fan, World Bank Division Director for Uganda, Kenya, Somalia and Rwanda, said the bank had added almost $2 billion in new financial commitments to Uganda over the past two years.
Uganda’s portfolio is among the largest International Development Association portfolios in Africa, Fan said.
About $3.1 billion remains available for disbursement, equivalent to roughly 5% of Uganda’s gross domestic product, he said.
Fan said the funds were aligned with Uganda’s Tenfold Growth Strategy, the National Development Plan and the World Bank’s FY2026-FY2035 Country Partnership Framework.
The framework focuses on governance, human capital, connectivity, private-sector productivity and job creation.
New projects have barely started disbursing
World Bank Senior Operations Officer Tonderai Fadzai Mukonoweshuro said six operations approved in Uganda’s 2025/26 financial year had added nearly $2 billion to the portfolio but had barely begun disbursing.
The figures highlight the gap between securing development financing and converting it into spending and completed projects.
The portfolio review is expected to produce project-specific actions aimed at speeding up implementation and improving the rate at which approved financing is converted into development results.