
Uganda has urged Italian companies to invest in coffee processing, pharmaceuticals, mineral refining and energy production, seeking to retain more value from its raw materials and create jobs at home rather than continue exporting largely unprocessed commodities.
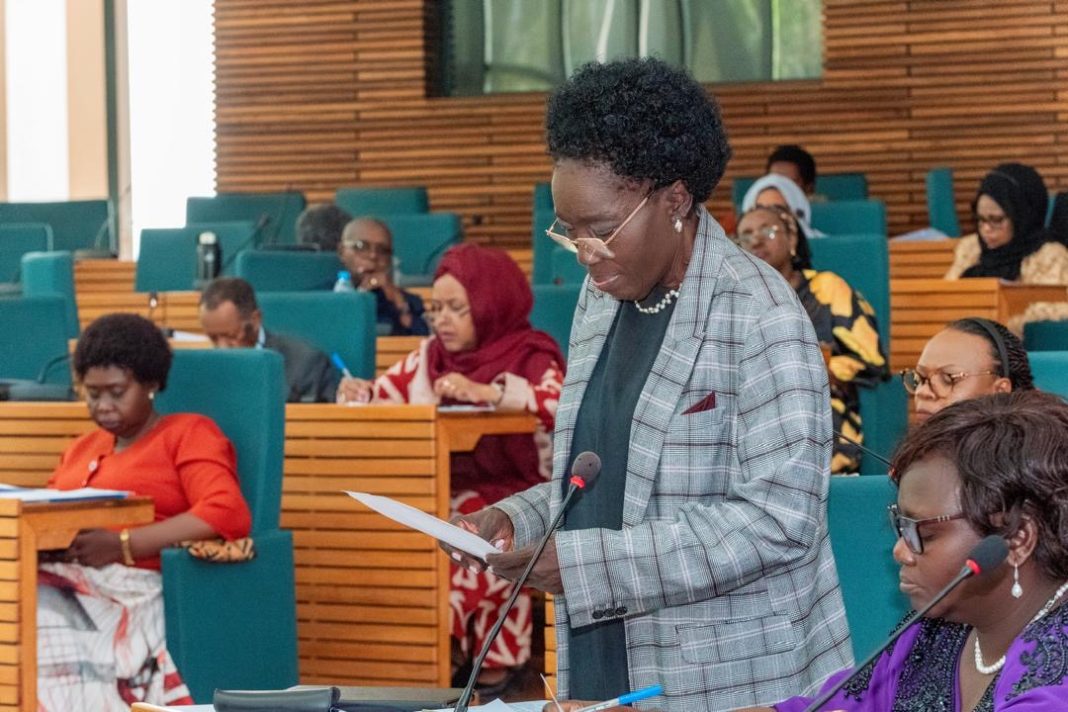
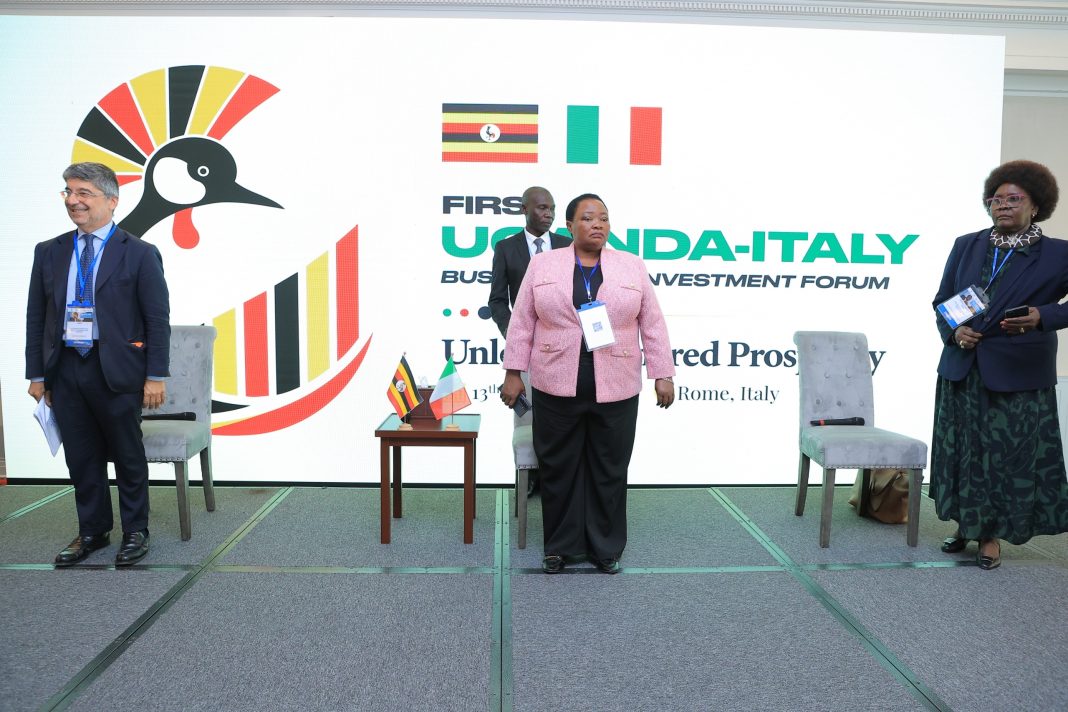
Prime Minister Robinah Nabbanja made the appeal at the opening of the first Uganda–Italy Business and Investment Forum in Rome on Tuesday, calling for partnerships that would move coffee roasting, packaging and other industrial activities closer to Ugandan farmers and producers.
“We want our people from Italy to take coffee made in Uganda. Not grown in Uganda,” Nabbanja told government officials and Italian business leaders at the Rome Cavalieri hotel.
She argued that processing coffee in Uganda would allow the country to capture a greater share of the value generated along the supply chain while creating employment for its young population.
Uganda exported 8.8 million 60-kilogramme bags of coffee in the year to April 2026, earning $2.4 billion, according to figures cited at the forum. Italy is Uganda’s largest coffee buyer, accounting for about a quarter of its coffee exports, officials said.
Nabbanja said Ugandan farmers continued to receive relatively little from selling raw beans compared with the value of finished coffee sold in overseas markets.
“That is where I want partnerships, so that we can help that poor Ugandan who makes you have a cup of coffee on the table,” she said.
The appeal reflects a broader government effort to shift Uganda’s economy from exporting agricultural and mineral commodities towards domestic manufacturing, value addition and higher-value services.
Coffee processing at the centre of the pitch
Gerald Kyalo, the commissioner for coffee at the Ministry of Agriculture, Animal Industry and Fisheries, said more than 12 million Ugandans depended on coffee for their livelihoods.
Uganda is Africa’s largest producer of robusta coffee, which accounts for about 89% of its output, while arabica makes up the remainder, he said. Italian buyers have purchased more than two million bags of Ugandan coffee annually in each of the past five years.
“You are our main market, and we are your most important supplier of coffee,” Kyalo told Italian buyers.
He said production had reached 9.5 million bags in the 2025/26 season and that Uganda was working towards a target of 20 million bags by 2030 through the distribution of additional seedlings to farmers.
The government also wants Italian companies to establish soluble coffee factories and other processing facilities in Uganda. Officials said exports would carry a national “Ugandan Coffee” brand and logo from the next financial year.
The challenge is to translate rising production into higher incomes for farmers. Increasing output alone will not guarantee that Ugandans capture more value if roasting, branding, distribution and retailing remain concentrated in overseas markets.
Kyalo said Uganda consumed only about 7% of its coffee production, leaving considerable scope to expand domestic processing and consumption.
He also sought to reassure European buyers about compliance with the European Union Deforestation Regulation, which requires relevant commodities entering the EU market to meet deforestation-related requirements.
Kyalo said Uganda had registered 1.5 million coffee farmers and mapped 1.6 million coffee gardens, with a target of mapping 2.6 million gardens by the end of December. A traceability system linking farmers, traders and a national data warehouse was being piloted, he said.
“We are ready for EUDR. Don’t lose sleep that you will not have coffee from Uganda,” he said.
Meeting the requirements will be important for maintaining access to European markets, although the effectiveness of the system will depend on reliable farm-level data, traceability and the ability of producers and exporters to demonstrate compliance.
Uganda offers 14% investment returns
Uganda Investment Authority Director General Robert Mukiza told Italian investors they could earn a 14% return on investment in the country, presenting Uganda as a base for serving markets across Africa.
“The most important market in the world, whether you want it or not, is Africa. You better get there now, and serve Africa from Uganda,” Mukiza said.
He pointed to Africa’s projected population of 2.5 billion by 2050, including an estimated 1.1 billion people in the middle class, as an opportunity for companies seeking long-term growth.
Uganda’s membership in the East African Community, the Common Market for Eastern and Southern Africa and the African Continental Free Trade Area, he said, offered investors access to wider regional markets.
Mukiza said investors undertaking value addition could benefit from serviced land in industrial parks, a 10-year tax holiday, duty-free imports of plant and machinery, and tax deductions for research and training, subject to applicable investment and tax requirements.
He also highlighted the authority’s one-stop centre, established under the Investment Code Act 2019, which coordinates services including business registration, tax identification, environmental certification and work permits.
However, the projected 14% return is an investment pitch rather than a guaranteed yield. Actual returns will depend on financing costs, operating expenses, market access, infrastructure and the performance of individual businesses.
Mukiza called on Italian financiers to help lower the cost of capital and support investment in electricity generation and transmission, which Uganda considers essential to its industrialisation ambitions.
Beyond coffee: pharmaceuticals, minerals and energy
Nabbanja presented Uganda’s broader Tenfold Growth Strategy as an opportunity for Italian businesses to participate in the country’s industrial transformation.
The strategy aims to expand the economy from about $50 billion to $500 billion by 2040, focusing on agro-industrialisation, tourism, mineral development and science, technology and innovation.
The prime minister said Uganda’s economy stood at approximately $69 billion and was growing at around 6% annually. She also outlined a government ambition to generate 52,000 megawatts of electricity by 2040, arguing that industrial expansion would require a substantial increase in power supply.
She invited Italian pharmaceutical companies to establish manufacturing facilities in Uganda, saying the Covid-19 pandemic had exposed the risks of depending on foreign suppliers for essential medicines.
The government is also seeking Italian participation in machinery manufacturing, cold-chain infrastructure, tourism, mineral processing and other industries.
Hez Kimoomi Alinda, executive director of the Uganda Free Zones and Export Promotion Authority, said the two countries had significant room to expand trade beyond coffee.
Uganda supplies Italy with high-grade robusta, which is commonly used in coffee blends, while Ugandan cocoa is exported largely in unprocessed form, he said. He urged Italian investors to establish factories producing cocoa butter, cocoa liquor and chocolate.
Other opportunities include dairy processing, aquaculture, fresh fruit and vegetables, vanilla, tea, spices, packaging and information technology-enabled services.
Alinda said inadequate testing laboratory capacity remained a constraint on Uganda’s fresh-produce exports to European markets. He invited Italian firms to invest in laboratories capable of helping exporters meet international standards.
He also offered Italian investors a free 1,031-square-metre production facility in Entebbe for value addition targeting Italian and other European Union markets.
Oil and minerals offer another investment frontier
Humphrey Asiimwe, chief executive of the Uganda Chamber of Energy and Minerals, invited Italian companies to invest in oil and gas, mining, electricity generation and related infrastructure.
He said Uganda had identified 58 minerals, of which 23 were commercially viable, including graphite, tin, tungsten and rare earths used in industrial production and clean-energy technologies.
“Uganda is at the precipice of first oil,” Asiimwe said, pointing to opportunities in refining, petrochemicals, fertiliser manufacturing and pipeline services as the country advances towards commercial oil production.
He also highlighted the proposed Kabalega Industrial Park near Lake Albert, a 29-square-kilometre development linked to a planned refinery with a capacity of 60,000 barrels per day.
According to a presentation by the Uganda National Oil Company at the forum, the park is projected to contribute nearly $5 billion annually to gross domestic product and generate more than 30,000 direct and indirect jobs. These are projections, not realised economic outcomes.
In the mining sector, Asiimwe said Uganda wanted investors to refine minerals locally rather than export ores and concentrates. He said gold, the country’s biggest export, was refined locally to a purity of 99.98%, and pointed to tax incentives for qualifying mining investments.
He also invited Italian companies to invest in electricity transmission, distribution and battery storage. Uganda currently relies heavily on hydropower, while further industrialisation will require investment in generation and the infrastructure needed to deliver electricity reliably to factories.
Italy signals interest in joint ventures
Italy’s Ministry of Foreign Affairs and International Cooperation representative Fabrizio Lobasso said Rome wanted to develop joint ventures with Uganda rather than limit the relationship to exports and imports.
He highlighted opportunities for collaboration in technology, skills development and digitalisation, and said an Italian foreign ministry delegation was expected to visit Uganda in early November.
“This morning I had my espresso, and inside the cup I didn’t see only coffee. I see the commitment of Ugandan farmers,” Lobasso said.
Giorgio Traietti, a board member of Confindustria Assafrica & Mediterraneo, said Italian companies viewed Uganda as a potential gateway to East African markets. The association plans to follow up with Uganda’s investment, energy and export-promotion agencies.
Uganda’s ambassador to Italy, Elizabeth Paula Napeyok, said the objective was to move relations beyond diplomacy towards commercial partnerships that could deliver tangible economic benefits.
Nabbanja also asked the Italian government to consider Uganda a priority country under the Mattei Plan, Italy’s framework for strengthening partnerships with African countries. She urged Italy’s state-backed financial institutions, including CDP, SACE and SIMEST, to support companies seeking to invest in Uganda.
Italy’s development cooperation agency, AICS, opened an office in Kampala in 2025 and identifies Uganda as a priority country for cooperation in areas including health, education, agriculture and environmental conservation.
The two-day forum, organised by Uganda’s embassy in Italy in partnership with Confindustria Assafrica & Mediterraneo, the United Nations Industrial Development Organization’s Investment and Technology Promotion Office in Italy, and Bergs & More Srl, covers energy, agro-industry, manufacturing, pharmaceuticals and healthcare.
It also promotes the proposed “Made with Italy in Uganda” concept, under which Italian manufacturers would establish operations in Ugandan industrial parks.
Turning investment promises into industrial jobs
The forum is part of Uganda’s Economic and Commercial Diplomacy Strategy for 2025/26 to 2029/30, which seeks to turn the country’s diplomatic missions into active platforms for export promotion, foreign investment, tourism and technology partnerships.
For Uganda, the central test will be whether the investment drive produces factories, skilled jobs, technology transfers and higher incomes for local producers, rather than simply increasing the volume of raw commodities exported.
Coffee illustrates the challenge. Uganda has an established production base and a major Italian market, but capturing more of the final selling price requires investment in processing equipment, quality control, branding, packaging, logistics and distribution.
Similar constraints apply to pharmaceuticals, minerals and fresh produce, where investors need reliable infrastructure, competitive financing, skilled workers and predictable regulations to make long-term commitments.
Nabbanja said the government would protect investors’ capital and profits under the law and that her office would intervene when companies encountered administrative obstacles.
The proposed partnerships could help Uganda move further into higher-value manufacturing while giving Italian companies a production base for regional markets. But the ultimate measure of success will not be the number of investment pledges made in Rome; it will be how much investment is realised, how much value remains in Uganda and how many sustainable jobs are created.